All Categories
Featured
Table of Contents
Their beliefs, worths, and efficiency remain consistent. Offering consumers with options is why they are still in organization. Most of the companies associated with debt consolidation are recognized by the Better Company Bureau and have A-plus scores. The BBB is often generous with its scores, but it's still a useful resource.
Make sure the business you choose has actually been accredited by the American Fair Credit Council or the International Association of Expert Financial Obligation Arbitrators. These organizations ensure business follow standards to protect customers from unfair financing practices or scams. A neglected however essential part of choosing a debt combination business is the instructional aspect.
The internal revenue service requires nonprofits to offer an instructional element to their service to maintain tax-exempt status as 501(c)( 3) companies. Nonprofits do this by offering credit therapy, nearly constantly at no charge. Counselors review a consumer's finances, focusing on the circumstances that caused financial problems and how managing budgets will resolve them.
Detailed Reviews of 2026 Relief Strategies
Contact the National Federation for Credit Therapy (NFCC) if you have questions on accreditation. The debt-relief business is no stranger to rip-offs. Be careful of the common red flags customers face when consolidating financial obligation. A few of the important things to look for when selecting a business or service consist of: Declaring nonprofit status when they're a for-profit business.
Seeking fees for services before reaching a written contract with your financial institutions. Using aggressive sales pitches, asking you to act rapidly on a decision that needs research study and time. Promising a "quick fix" solution. All debt relief programs take time, the majority of them in between 3 and five years. Be suspicious of companies assuring faster outcomes.
Ways to Erase High-Interest Debt in 2026Don't settle for your very first deal. Use the info you collected to the financial situation you're facing and make sure it resolves the issues. Suppose you have adequate income to pay down debt but need a customized regimen or kind of instructions to get begun. A debt management program might be better than a debt consolidation loan or debt settlement.
Understand the benefits of the service you select. It is very important to discover a program that provides the kind of debt consolidation you want, makes you feel comfy dealing with their staff and requirements, and informs you while you remain in the program to limit future setbacks. Debt consolidation programs can remove debt in 3-to-5 years.
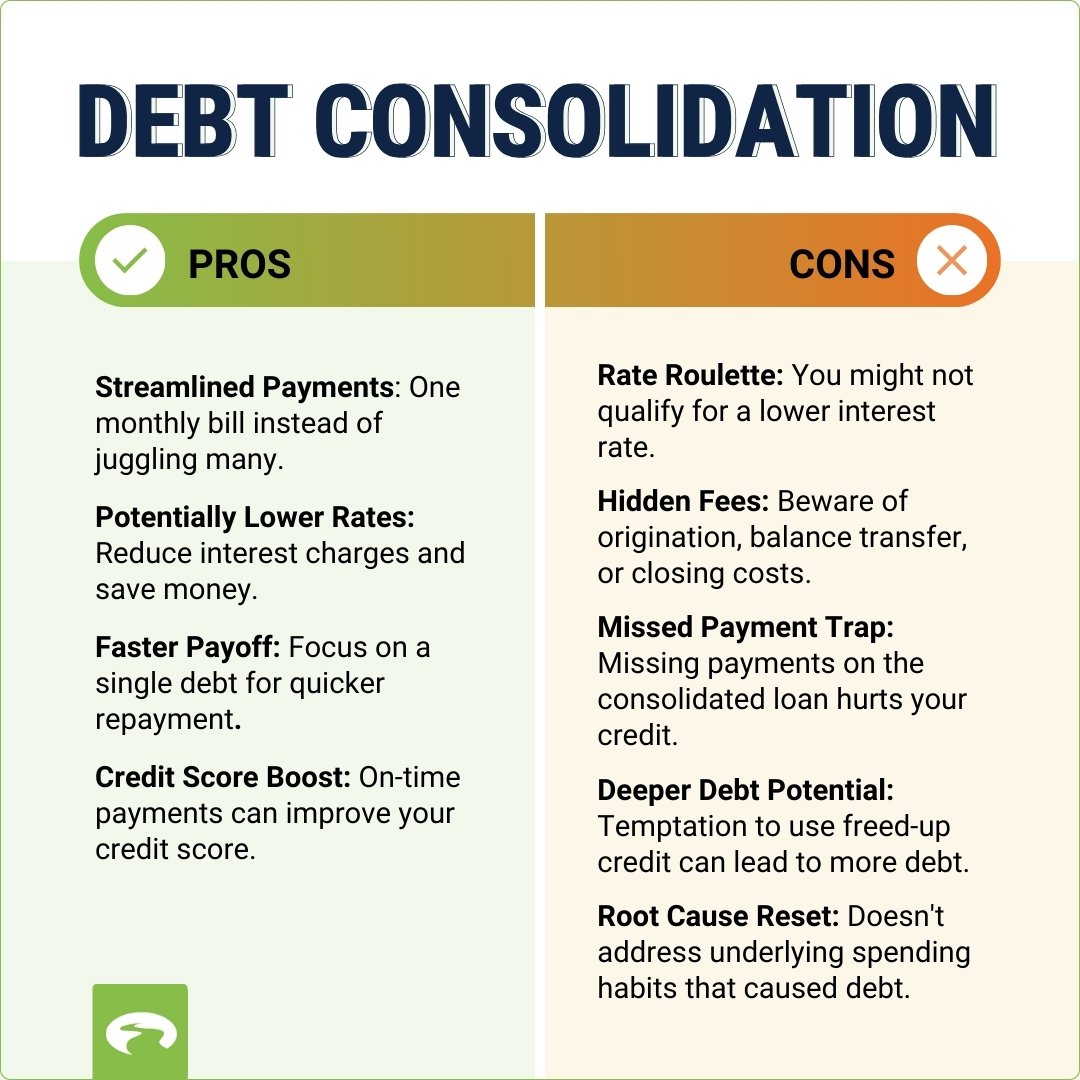
Benefits and Risks of 2026 Credit Consolidation
You likely didn't get into debt in a hurry. Focus on making good costs options and on-time debt payments. Eliminating financial obligation is a rewarding obstacle.
Debt combination works for consumers with stable earnings, frequently no matter credit history, but not everyone will certify. Some might not make adequate to cover the month-to-month payments, while others may find alternative services to work better for their special scenario. Credit therapists can notify you of your alternatives and let you understand whether debt consolidation remains in your finest interest.

Credit therapy is a free or inexpensive service provided by financial obligation combination business. They might suggest enrolling in a debt management program or participating in housing or personal bankruptcy therapy.
Increase the payment procedure by incorporating the debt snowball or debt avalanche Remember to utilize a loan calculator when factoring monthly payments. let you move the balance from debt-heavy charge card to a brand-new charge card with a low-interest rate. Numerous customers will discover offers for 0% interest between 12-18 months.
Navigating Urgent Financial Help for Struggling Households
Bear in mind transfer fees generally balancing 2% to 3% of the debt moved. If you're a homeowner, consider a home equity loan or home equity line of credit. These provide lower rate of interest than numerous options, but your home will be at threat must you default on payments. The majority of people can borrow approximately 50% of their 401k and have up to 5 years to pay it back before the IRS smacks them with an early withdrawal penalty.
The timing of available funds upon loan approval may differ depending upon your bank's policies. Loan amounts range from $2,000$50,000. Citizens of Massachusetts have a minimum loan quantity of $6,500; Ohio, $5,001; and Georgia, $3,001.

Latest Posts
Ways to Erase Credit Card Debt in 2026
Comprehensive Debt Consolidation Analysis for the New Year
2026 Expert Analysis to Successful Debt Resolution